
For a sari-sari store owner with steady customers, the hardest part of borrowing may have little to do with whether she can repay. Without collateral or a conventional credit history, even a viable business can remain invisible to traditional lenders. Tala was founded to address that gap between economic potential and formal credit.
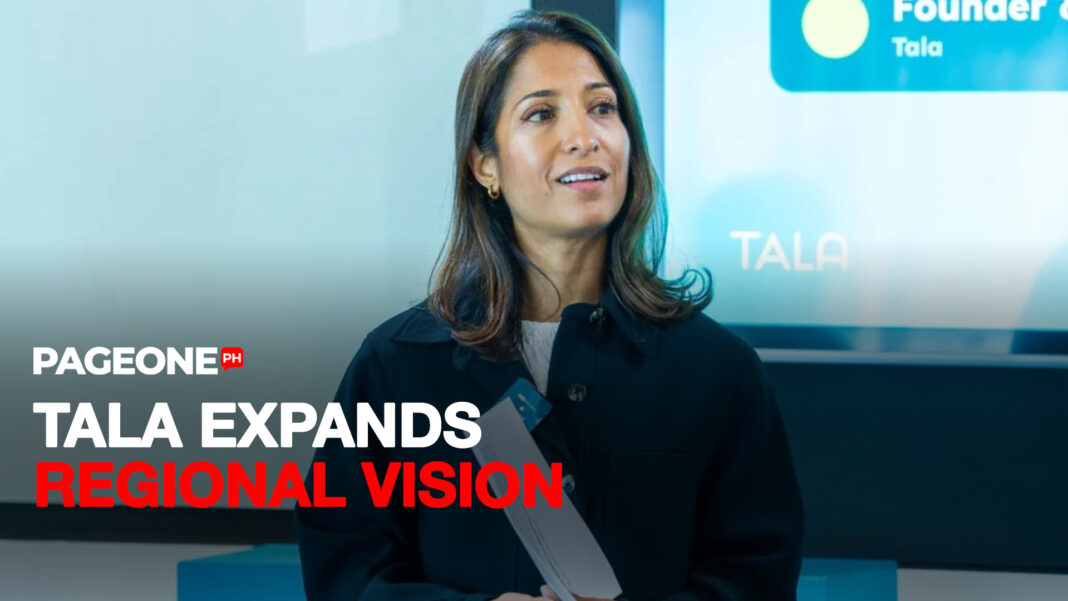
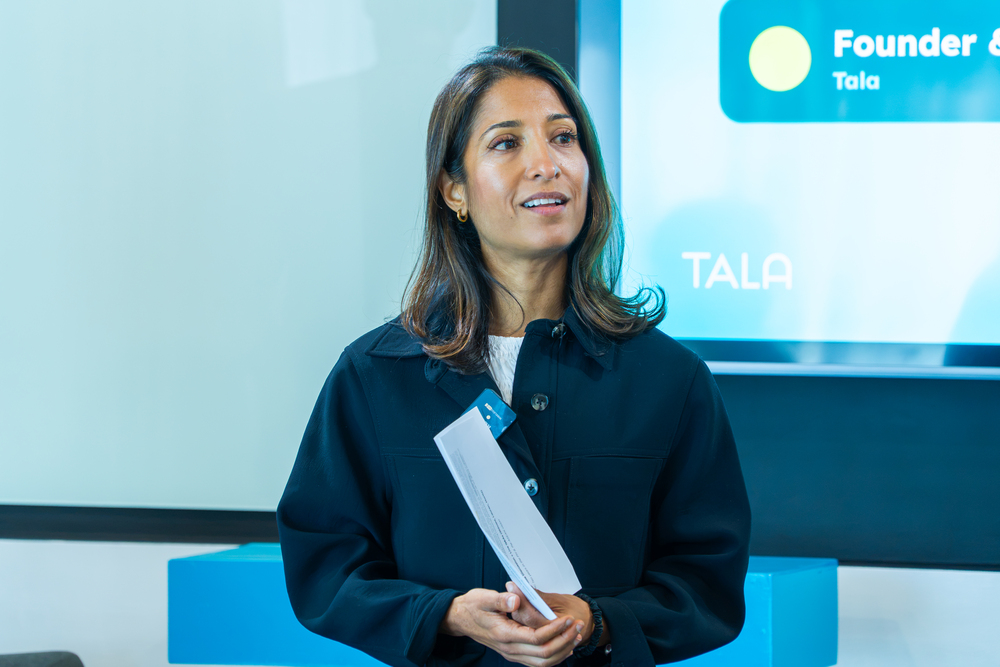
At a media roundtable held in Makati, Tala founder and global CEO Shivani Siroya outlined how the AI-native credit infrastructure company’s mission has evolved from expanding access to building long-term financial agency. Joined by SVP for Global Brand and Corporate Affairs, Lauren Pruneski, and Tala Philippines President and General Manager, Moritz Gastl, she highlighted the Philippines as a strategic foundation for ASEAN growth ahead of its local 10th anniversary in 2027.
The global challenge helps explain that shift. The Atlantic Council’s 2026 report, A Three-Billion-Person Challenge, found that 75% of adults in low- and middle-income economies have a financial account, yet only 24% borrowed from a formal provider in the preceding year. Tala describes the roughly three billion people underserved by traditional finance as the Global Majority. Their limited access to suitable credit can hold back households, businesses, and grassroots economies.
Turning Access Into Opportunity
To help close that gap, Tala uses alternative data and proprietary risk intelligence to assess people whose creditworthiness conventional records may not capture. Rather than treating a limited credit history as a measure of potential, Tala’s approach brings formal financing closer to people already working and earning. The goal is not simply a loan, but greater confidence and control over financial decisions.
For Berla, a Tala customer from Baseco, Manila, that opportunity meant creating her own livelihood. ‘I told myself if nobody will give me an opportunity, then I’ll create opportunities for myself,’ she said. After struggling to find work, she used Tala credit to start a sari-sari store while supplementing her income by transporting goods by boat.
Her experience reflects wider customer outcomes. Research by independent firm 60 Decibels found that 91% of surveyed Tala borrowers in the Philippines reported an improved quality of life, including a greater ability to cover household expenses and bills. These findings reinforce Tala’s view that inclusion should be measured by what customers can do with credit, not simply whether they can obtain it.
Making Dignity The Foundation For ASEAN Growth
The Philippine market also offers evidence that this approach can work at scale. According to Tala, it has served more than five million Filipino customers and maintains a 90% repayment rate. Nearly a decade of underwriting, customer engagement, and collaboration with the Bangko Sentral ng Pilipinas and the Securities and Exchange Commission, has made the market an important reference point for its ASEAN strategy.
Central to that experience is Debt with Dignity. Launched in 2025 in the Philippines and now expanding to Tala’s other markets. Debt with Dignity is Tala’s commitment to treating borrowers fairly throughout the lending journey. Clear fees and terms, repayment dates aligned with customers’ cash flow, and collections that protect privacy and prohibit harassment help build trust alongside access. Financial education and fraud prevention further support customers in making informed decisions.
Tala is extending these principles through its Global Debt Collection with Dignity Initiative, which proposes model standards that regulators can adapt. In the Philippines, the company works with regulators and industry groups on consumer safeguards – reflecting a broader effort to strengthen consumer protections through collaboration.
This collaborative approach further supports Tala’s efforts to unleash the economic power of the Global Majority by expanding responsible credit access through the combination of institutional capital with its credit infrastructure; while Credit-as-a-Service is designed to assist banks, wallets, and other platforms in providing financing through channels that customers already utilize. Together, these relationships help address gaps in funding and access while creating opportunities to reach more borrowers across different markets.
Building on nearly a decade in the Philippines, Tala aims to bring its technology, consumer protections and partnership model to more ASEAN markets. The ambition is to expand the economic opportunities that credit can create while keeping dignity and financial agency at the center of growth.